Key takeaways
- A seasonal schedule concentrates payments in your high-revenue months and lightens them in the off-season.
- It is a structuring choice made when the file is set up, not a renegotiation after the fact.
- Farms, snow removal contractors, landscapers and tourism operators are the classic fits, but any documented cycle qualifies.
- The application is the same 3 steps as any equipment file; the schedule is designed around your revenue pattern.
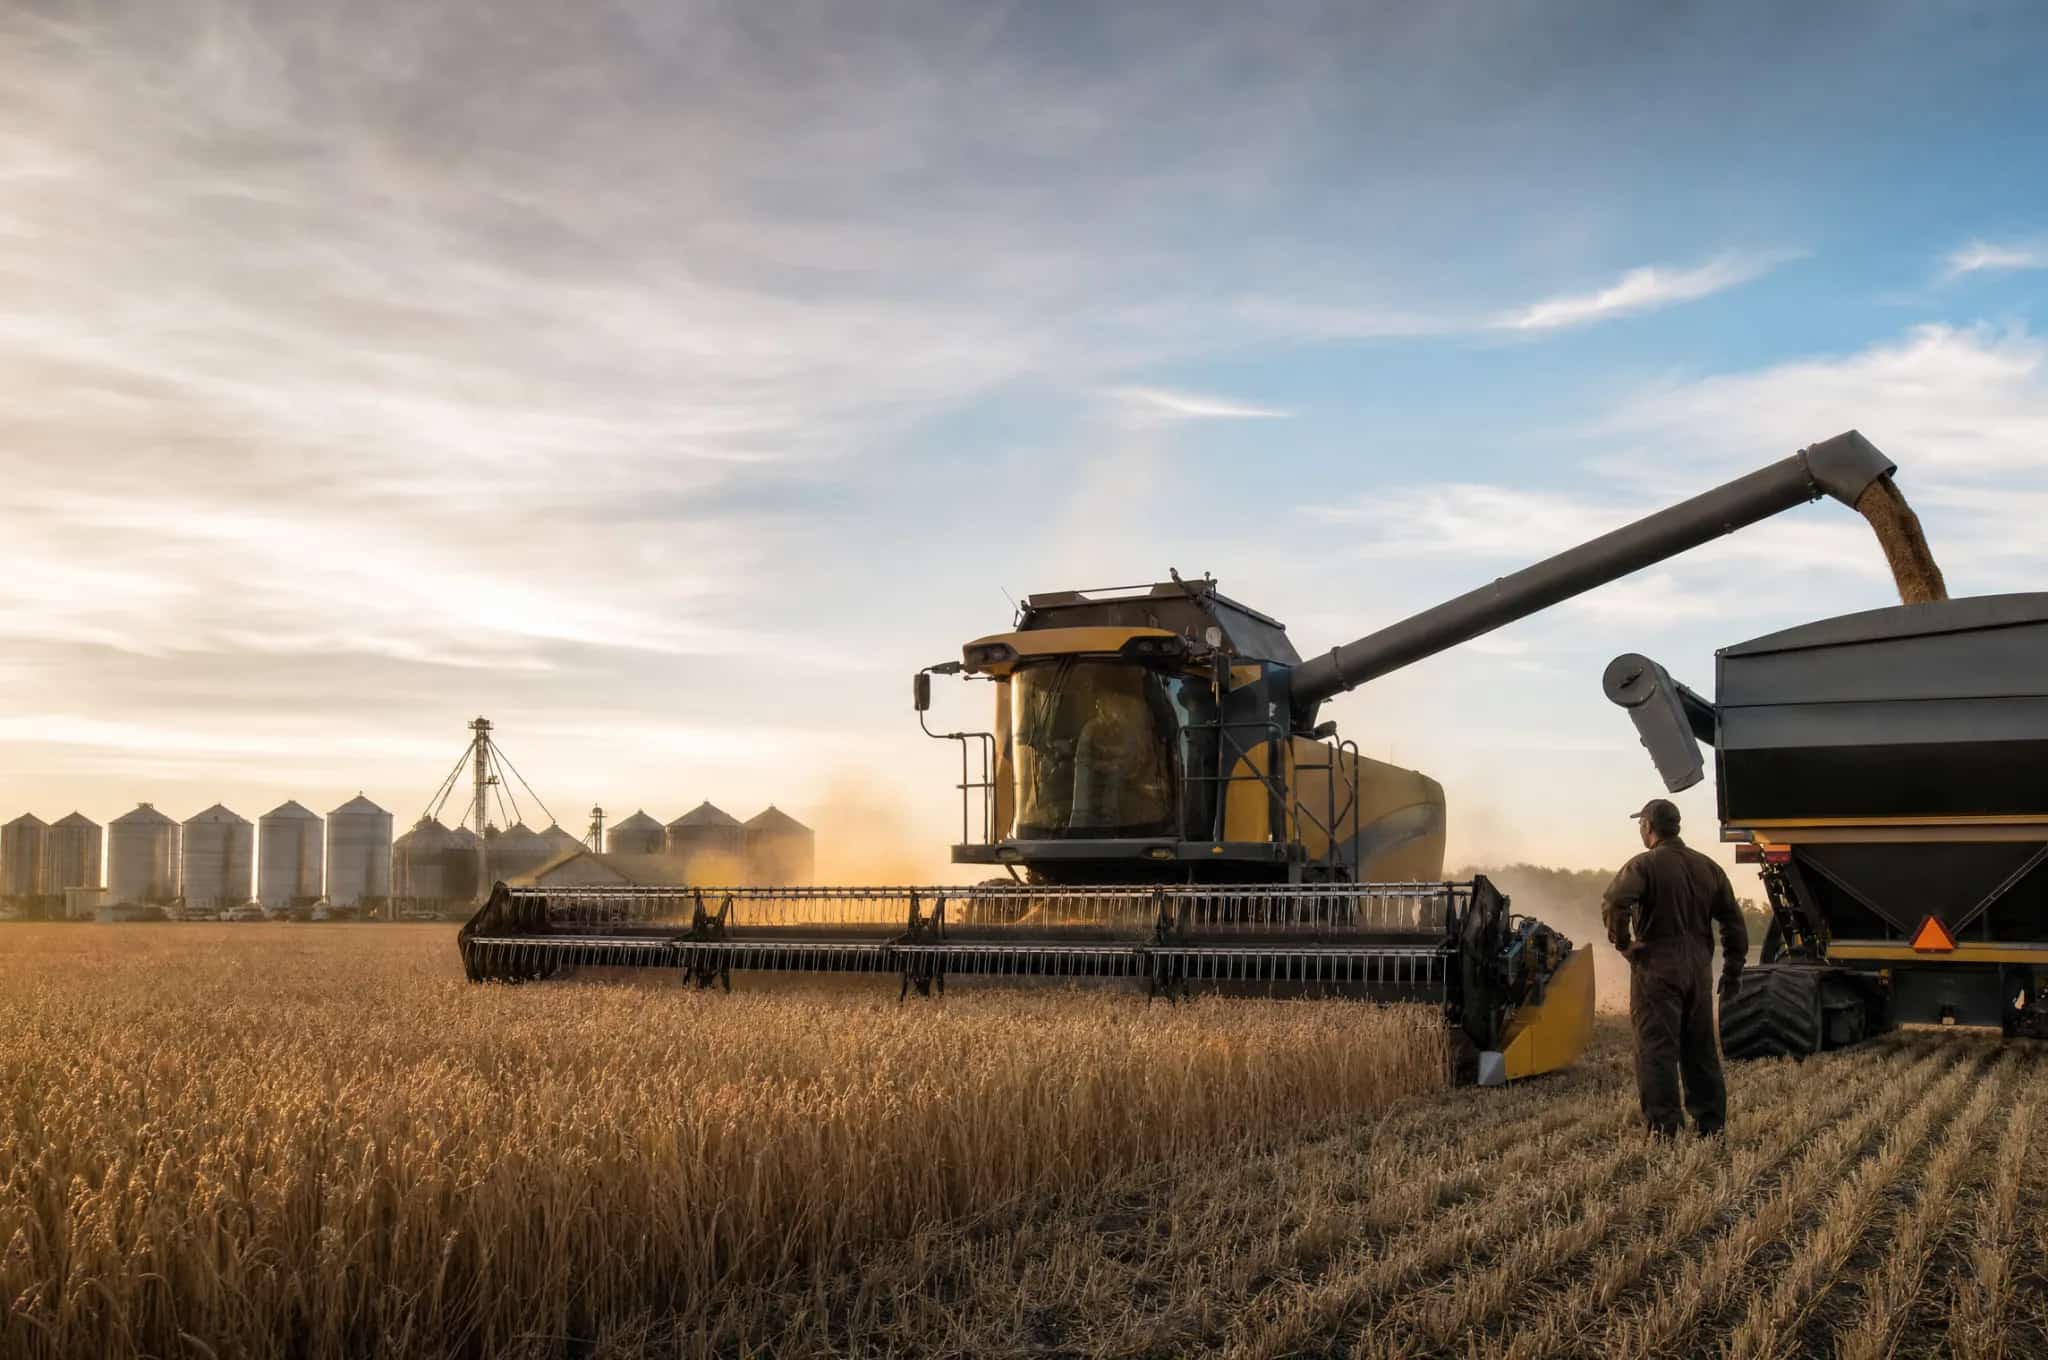
A flat monthly payment assumes flat monthly revenue. Plenty of Canadian businesses do not work that way. A grain farm collects most of its income after harvest, a snow removal contractor invoices through the winter and parks the fleet in June, and a whale-watching operator in the Maritimes earns in the summer window and holds on through the rest of the year.
Asking these businesses to make the same payment in their dead months as in their peak months strains cash for no structural reason. The financing industry has an answer for this, and it is older and more ordinary than most owners realize: shape the schedule to the business instead of shaping the business to the schedule.
How seasonal payments work on an equipment file
A seasonal payment schedule shapes the financing contract around your revenue curve. Payments are concentrated in the months when money comes in and reduced, sometimes substantially, in the months when it does not. The total obligation over the term is the same; the timing is what changes.
Owners sometimes assume this flexibility must cost something hidden. It is better understood as risk alignment: a lender would rather receive payments when your account has money in it than chase a missed payment in your dead season. A schedule that matches the business is safer for both sides, which is exactly why lenders who know cyclical industries offer it.
This is a structuring decision made when the file is put together, not a favour requested later. When the application lands, the file is built around variables that include your industry and your cash-flow pattern, and it is routed to lenders comfortable with that structure. Some funding sources handle seasonal schedules routinely, others simply do not offer them, and part of a broker's job is knowing which is which before the file goes out. Applying directly to a lender that only writes level schedules gets you a level schedule, whatever your revenue curve looks like.
The mechanics of the application do not change. It is the same 3 steps as any file: identification, owner information, then the equipment. Smaller transactions are usually decided on the application alone, and files above $250,000 need financial statements. Those statements actually help a seasonal file, because they show the lender the cycle you are asking the schedule to follow.