What we finance, and who funds it
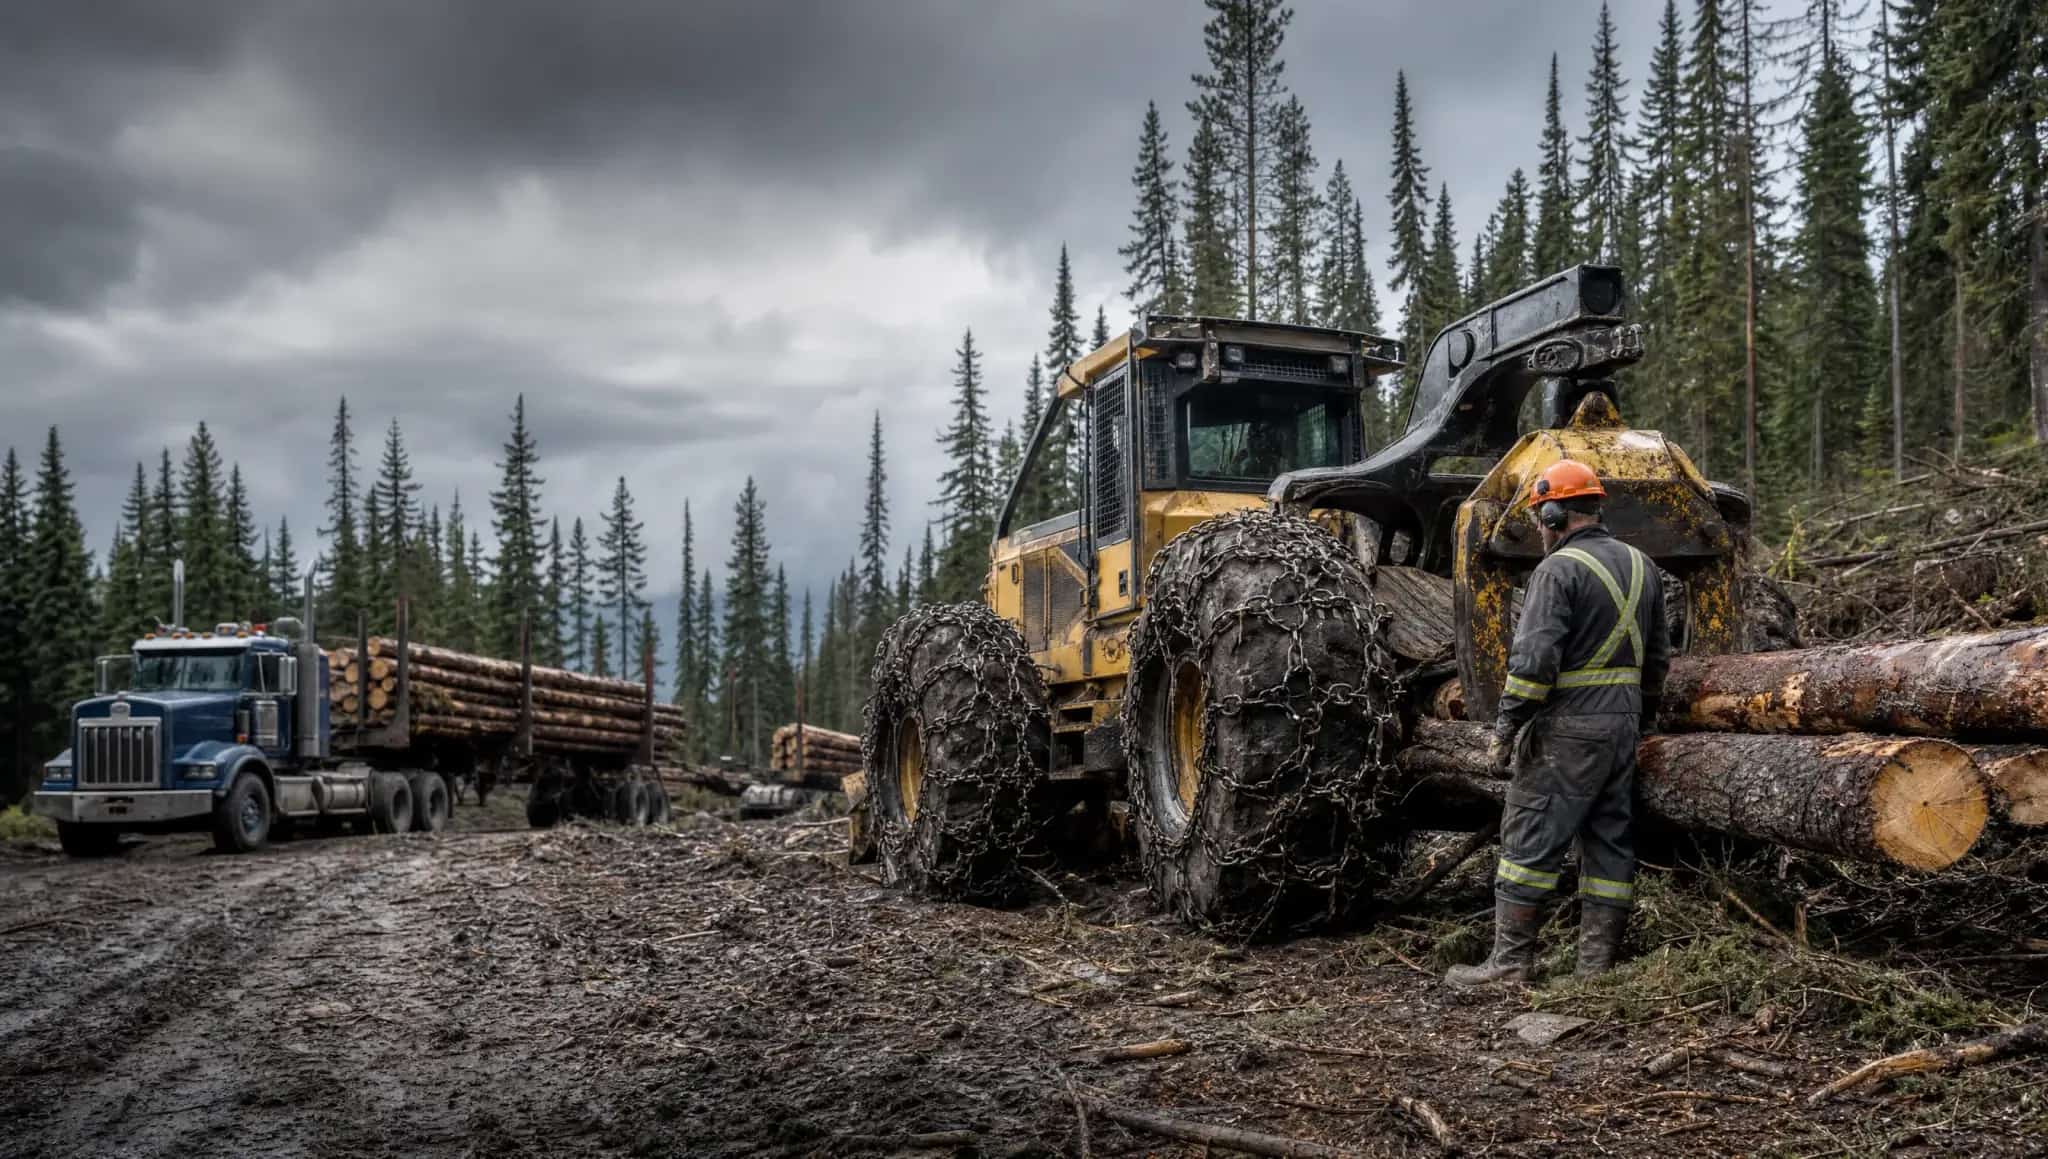
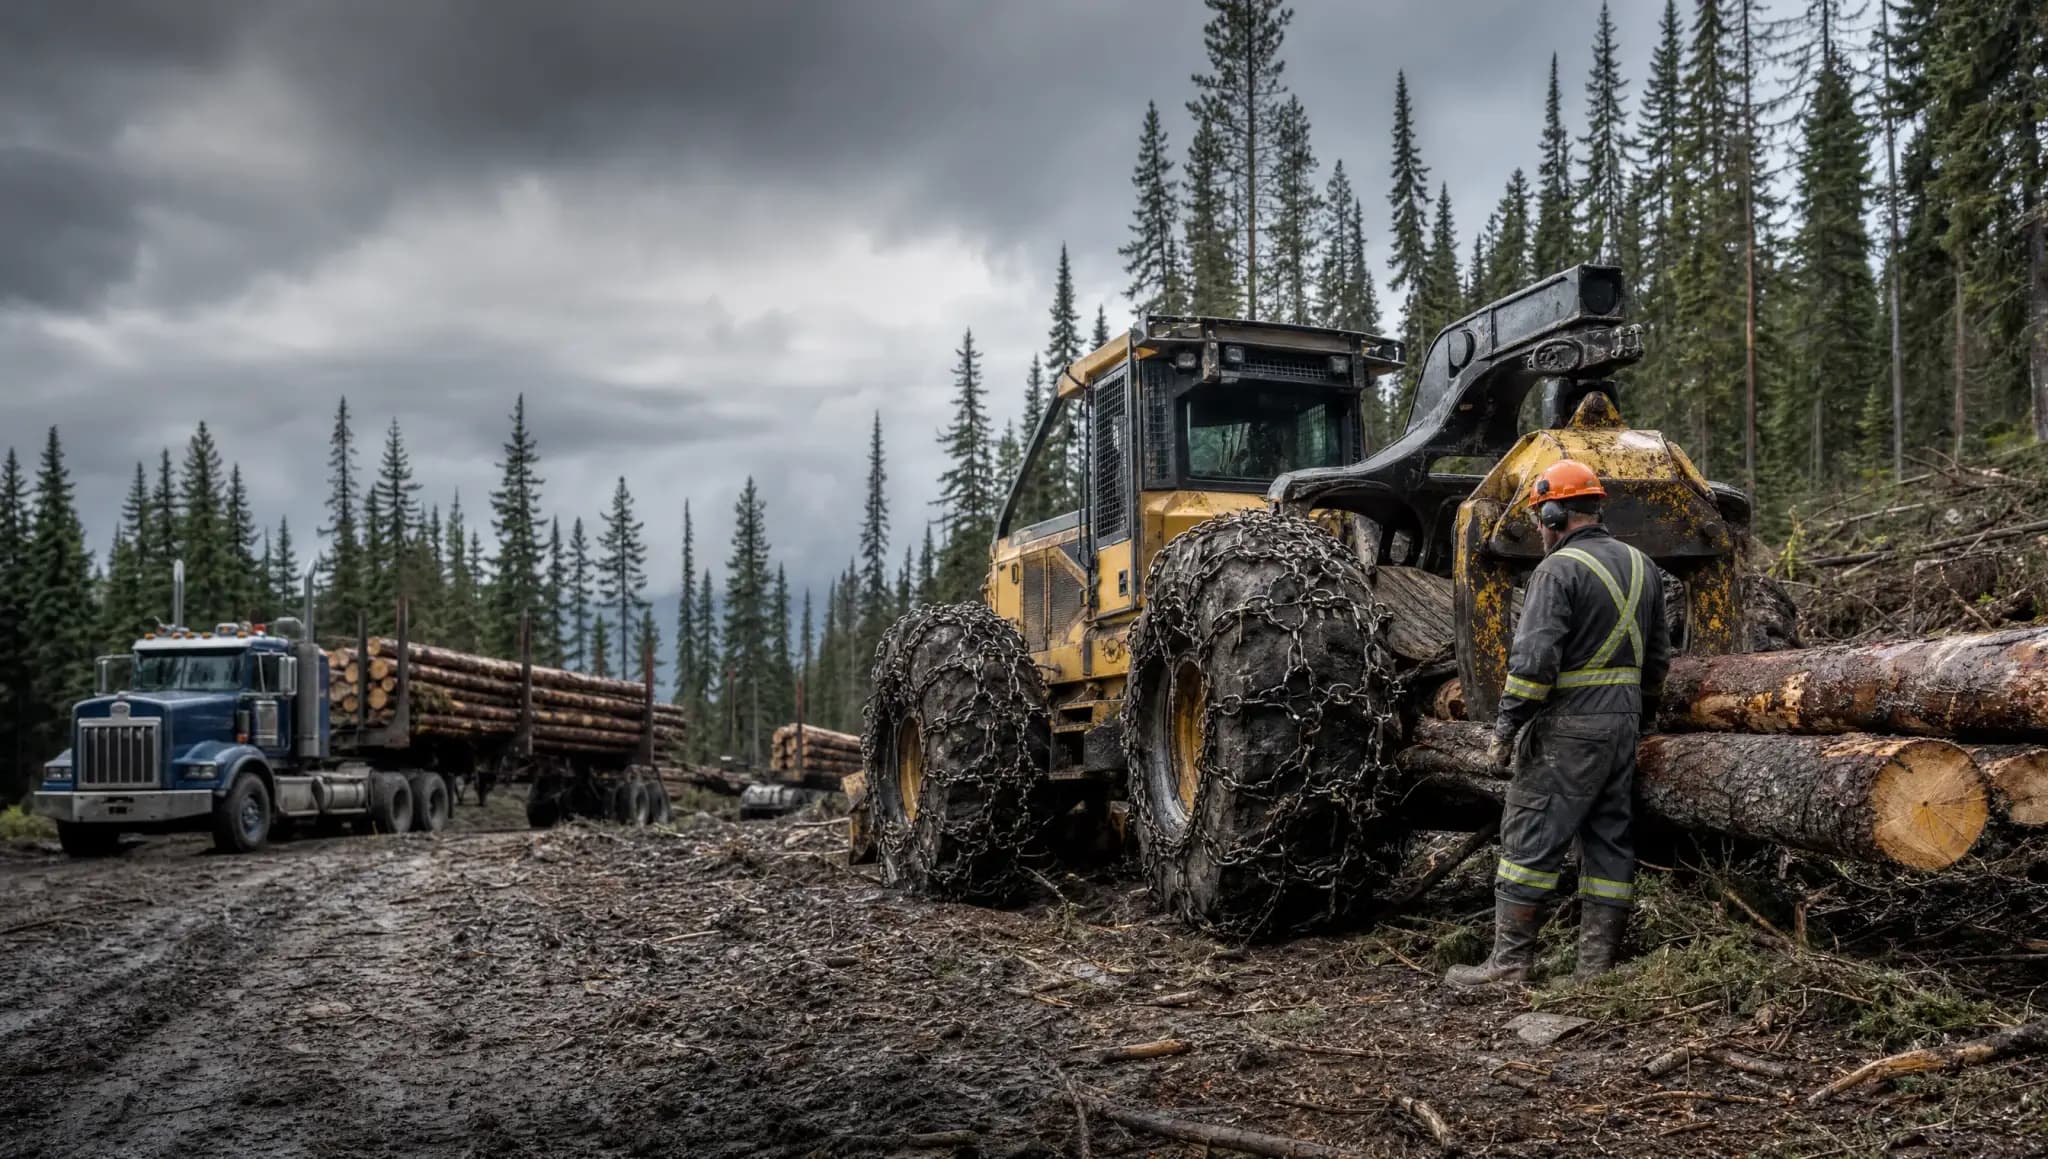
We arrange forestry equipment financing through major Canadian banks and specialised leasing institutions that actually understand the sector, which matters because forestry is not a generic credit. Lenders unfamiliar with logging see remote worksites and hard use; lenders in our network see machines with established resale markets and contractors with mill contracts behind them. Harvesters and feller bunchers, forwarders and skidders, chippers and grinders, and sawmill and processing equipment all qualify, new or used, from a dealer or a private sale. Used forestry iron with a documented service history finances well.
Cash flow that follows the cut
Cash flow in forestry follows allowable cut, weather and mill demand, none of which run on a calendar year. Seasonal payment structures fit contractors who shut down for breakup or fire season, keeping payments light when the machines are parked. Contractors who own their fleet can use sale-leaseback to free capital for a new contract's mobilization costs. Startup structures exist for experienced operators going out on their own with a first machine, a common path in this industry.
The operating case for newer machines
The operating case for newer equipment is direct: fuel burn, uptime and operator comfort all improve, and in a sector where a mechanical failure can idle a whole crew at a remote block, reliability is revenue. Environmental and safety requirements on active blocks also keep tightening, which favours current machines. Applications above $250,000 require financial statements, and we tell you up front what the file needs. Which lease structure suits better depends on tax treatment and how long you run your iron before trading. Send us the machine and the contract it will serve, and we come back with real terms.